OCIO directory, fall 2026: think service
by charles | Comments are closed10/14/2026
If you don’t take care of your customer, your competitor will. —Bob Hooey, Make ME Feel Special!
Our fall 2026 Outsourced Chief Investment Officer (OCIO) directory features one hundred-five service providers with names, numbers, and emails for each firm.
Our goal is to give new business prospects – pensions, nonprofits, and family offices – an easy, ad-free, no-paywall, no-charge way to find OCIO firms and connect with the right representative.
Relentless growth
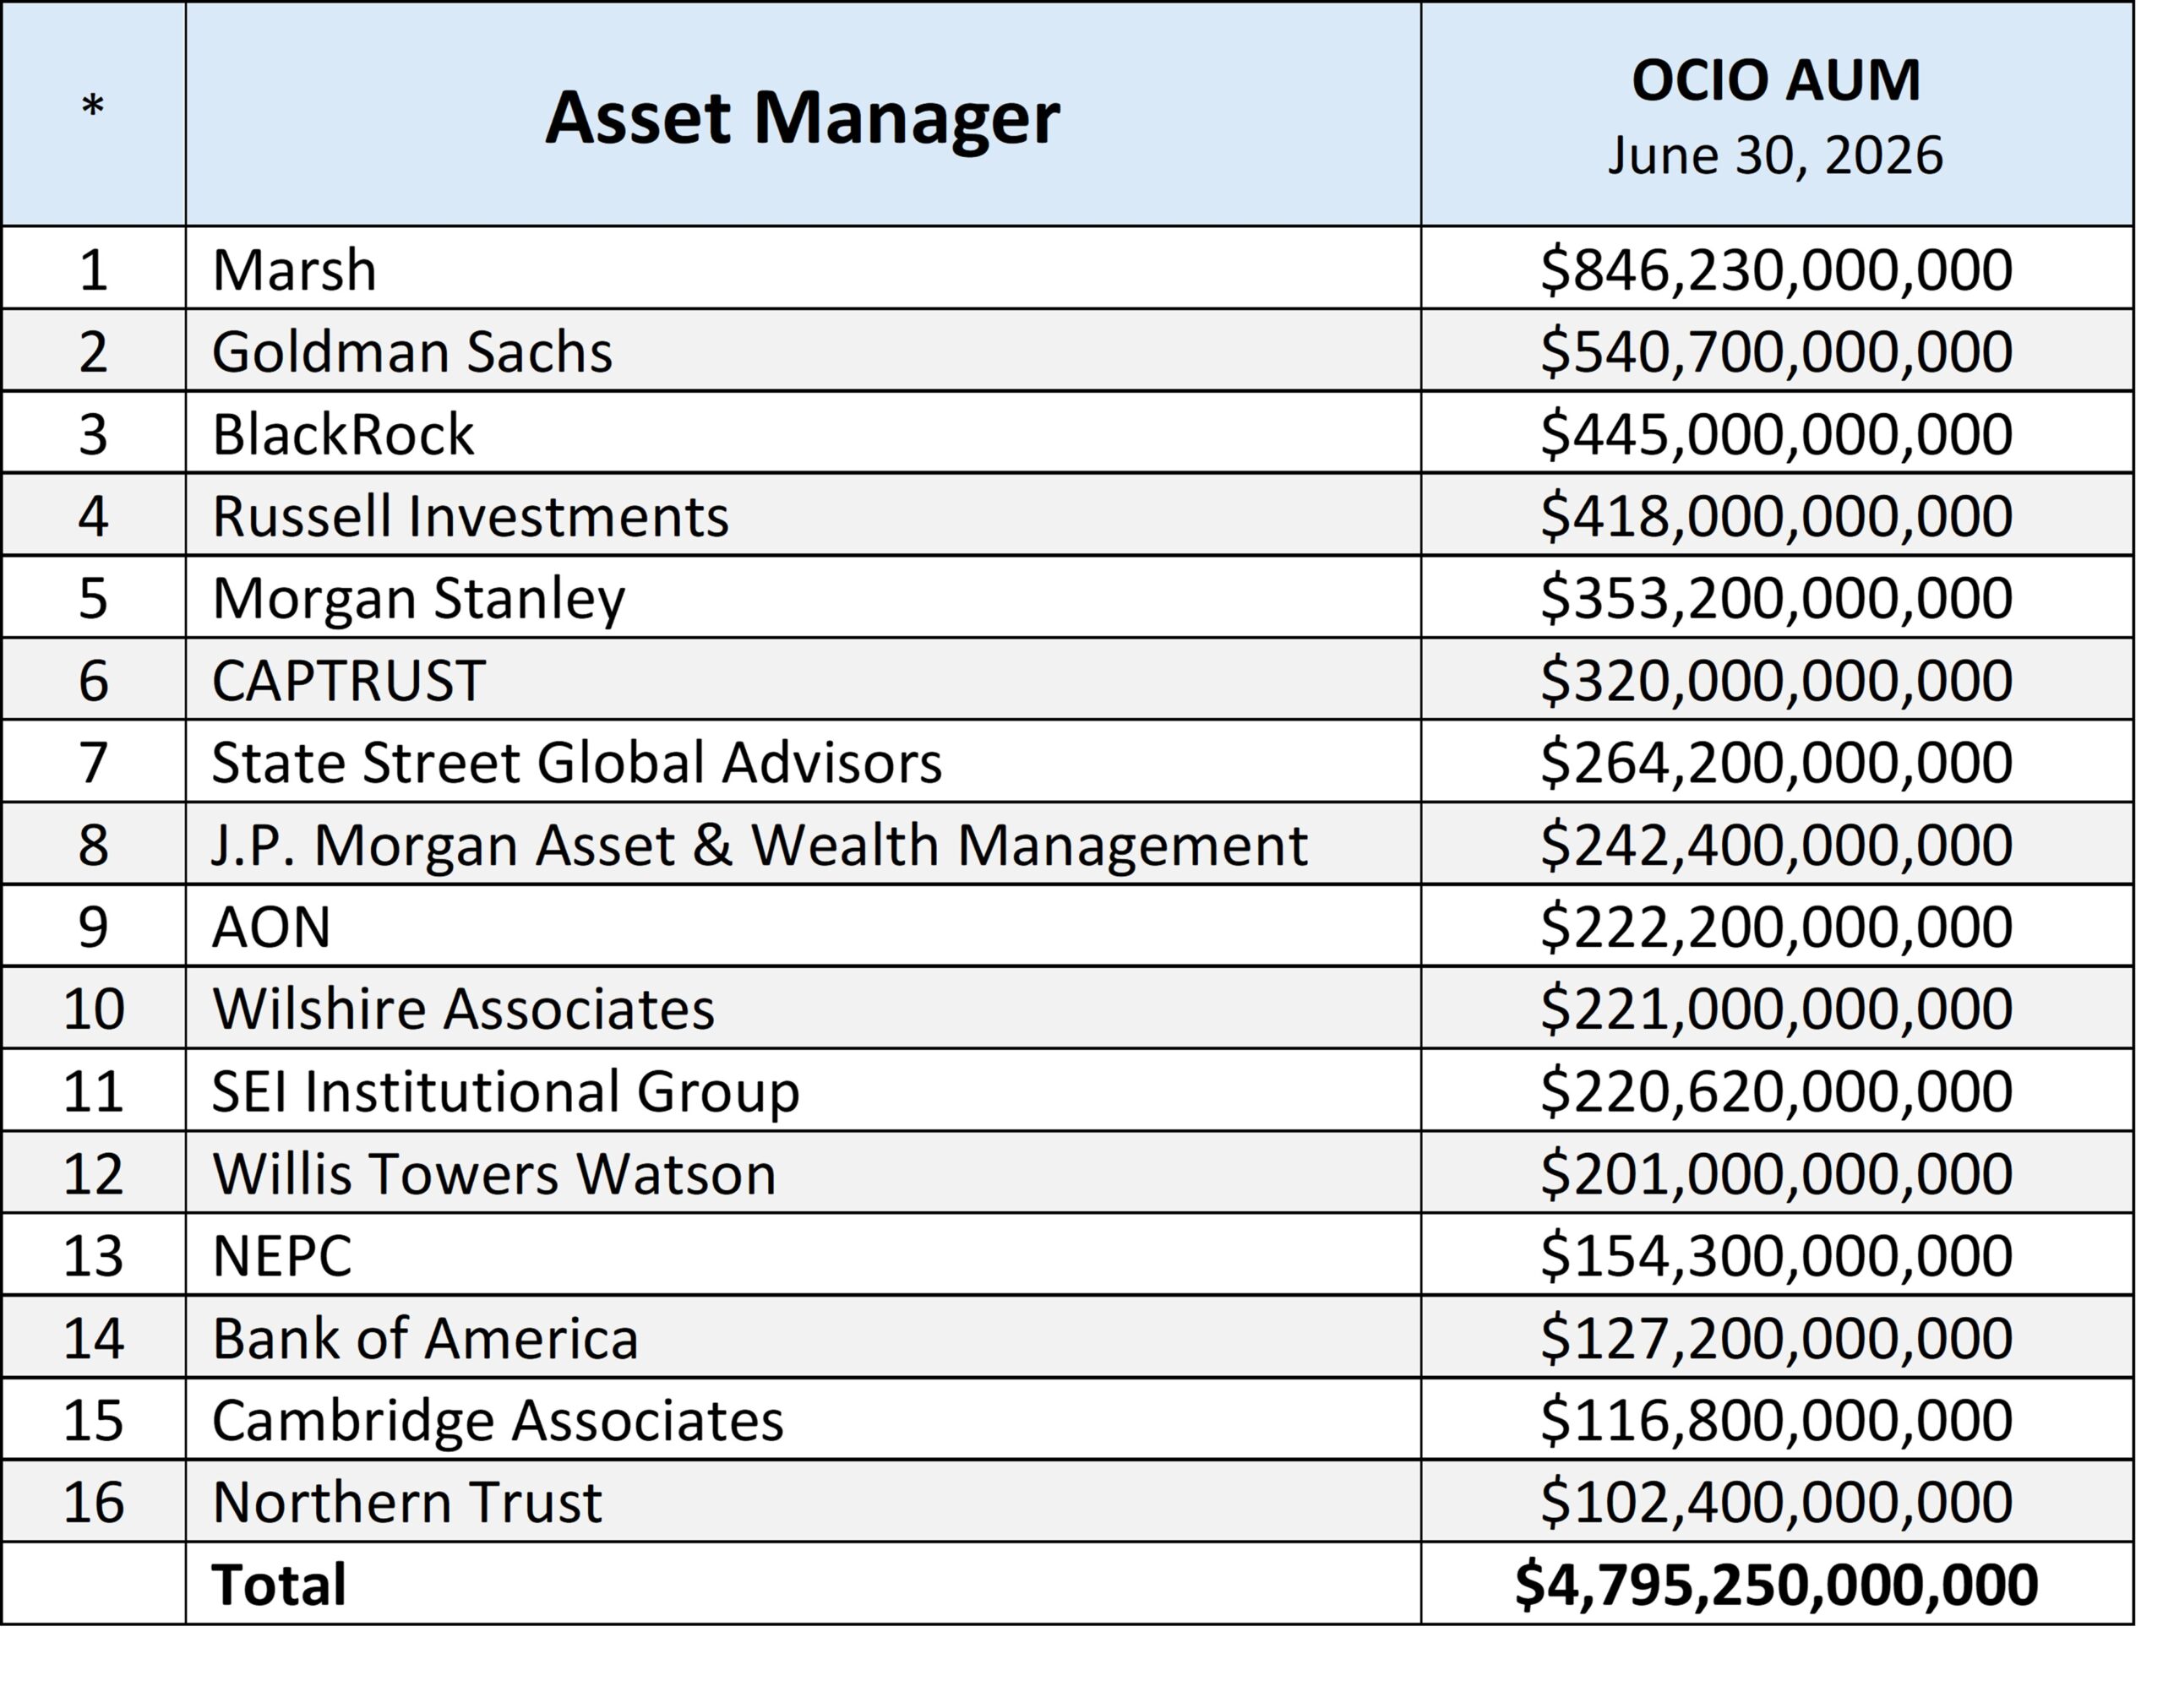
AUM topped $6.3 trillion as of June 30, 2026, an 11.8 percent jump ($666bn) from just six months ago. And, as usual, the big got much bigger. Sixteen firms over one hundred billion manage about seventy-six percent of the assets (mostly pension assets) leaving the remaining trillion-five for independents and boutiques.
Looking back over the last four decades, the best time to pitch an outsourced OCIO proposition was probably about thirty years ago. Fewer competitors, better margins, plenty of prospects. But there’s still runway ahead for the go-getters. Here’s a rough estimate of total investable assets for the nonprofit, non-pension market:
$1.786 trillion – private foundations
$0.177 billion – community foundations
$1.000 trillion – endowments
$0.600 billion – hospitals, health systems
$0.300 billion – religious organizations
$0.070 billion – museums
$3.933 trillion
The corporate defined benefit business is a land unto its own, actuarial, regulated, and liability driven, with a focus on funding levels and cost reduction. Better to let Marsh, Goldman, Blackrock, et al., deal with those headaches.
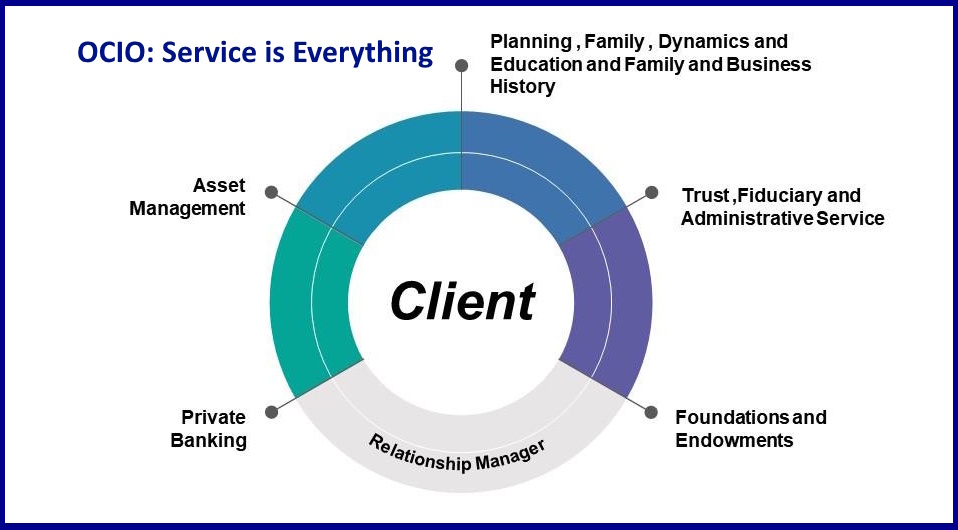
New business for most OCIOs will come from private wealth and related foundations, a booming market. But when it comes to the moneyed class it’s all about service.
Speaking of service
A sizable southern foundation called a few weeks ago to discuss their OCIO’s poor service. Didn’t matter that the 10-year investment performance was excellent – our data put them in the top third. According to the board their OCIO responds late to their requests and pays lip service to their concerns. They were here to talk about a change.
When families are asked what qualities are most important in a client service advisor, trust and responsiveness top the list. And yet, after twenty years working with OCIOs – recruiting, consulting, M&A, this directory – poor service and communication is today’s number one complaint.
Maybe it’s turnover and the lamentable loss of passion and focus. Once a founder sells it’s hard to sustain that intensity and vision. Most OCIO trailblazers have been in business for thirty to forty years, some longer, and many are aging out.
Unless an OCIO is family-owned like Hirtle & Co. with succession in place, or that rare private partnership with a two-hundred-year-old history like Brown Brothers Harriman, merging is usually inevitable.
With heady valuations, it’s hard to say no to a generous offer. In the last few years, Hall Capital, NEPC, Agility, Truvvo, Ellwood Associates, New Providence, CornerStone, PFM, and Permit Capital, among others, have snuggled up to big money patrons.
Mr. Hirtle, industry doyen and long-standing client, describes the challenge this way:
Over the past decade and more, markets have been so consistently productive that almost everyone is capturing historically strong returns. So, differentiation in our business depends on exceptional professional service.
Daniel Kahneman famously differentiated the perfectly rational humanoid “econs” of the economic textbooks – who only care about performance – from real people with real everyday emotions, pressures, and concerns which he called “humans”.
Exemplary service means focusing on our clients’ success and well-being, those human elements Professor Kahneman describes. Our mission is to ease their minds and help keep their commitments. We never want to disappoint them. That means both strong performance and great client care.
—Charles Skorina
Read More »Better boards, busy bots
by charles | Comments are closed07/29/2026
Making money is art –Andy Warhol
Today’s newsletter is short and mostly sweet. First, helpful hints on building great boards and investment teams, but then some doubts on how much longer it might matter as bot-views and agentic overlords commandeer portfolio management.
Board work matters
A pithy primer on Washington University’s remarkable investment resurgence posted recently on LinkedIn. Clark Hoover, investment officer at the Los Angeles City Employees’ Retirement System read our report on the WashU endowment board’s laudable work and thoughtfully excerpted key dos and don’ts for his nonprofit peers.
When insights come our way – from in-depth interviews with industry veterans, for example – we feel obliged to pass them on to our savvy readers. As ‘frontier’ novelist Louis L’Amour wrote “Knowledge is like money: To be of value it must circulate.”
“What the best boards do:
- Stay aligned and engaged — committed, collaborative, and focused on long-term success.
- Keep governance lean — typically 5–7 members, low turnover, and average board tenure of 10+ years.
- Provide strategic clarity — establish clear objectives, define expectations for the investment team, and evaluate and compensate staff objectively.
- Focus on governance, not management — the board owns strategic asset allocation while empowering investment staff to execute.
What weaker boards tend to do:
- Overcrowd the boardroom — too many voices, high turnover, and excessive micromanagement.
- Send mixed signals — discourage prudent risk-taking while expecting outsized returns.
- Underinvest in talent — reluctance to pay competitively often leads to weaker performance and higher staff turnover.
Strong governance doesn’t guarantee strong investment results—but weak governance makes results much harder to achieve.”
One reader noted, however, that public pensions often have slots set aside for government and union representatives which crowd the boardroom. When it comes to public plans and their financial sway, everyone wants a seat at the table.
Iconoclasts are few and far between and CIOs on many campuses have little room to run, even when they want to. So, if most institutional portfolios look and act the same, why not just give in to AI and the algorithms? It’s cheaper, easier, and when something goes wrong, blame it on those ghosts in the machines.
Sophisticated quant strategies proliferate on Wall Street, ETFs have taken over Main Street, and AI chatbots and robo-advisors swarm financial services. In the world of HR and talent acquisition, algorithms and predictive tools are here in force and impact hiring and career advancement.
Our cyber symbiotes don’t just ease the workload they free us from the tyranny of choice. Decisions without responsibility or regret, every bureaucrat’s dream.
But there are always tradeoffs. Disruptive innovation hits hard and the effects can be brutal. As the automobile swept America, replacing the real life power of horses, entire industries collapsed. Stables, blacksmiths, harness makers, feed suppliers, auction houses, investors; so many livelihoods gone.
So, here’s my worry. These AI dislocations affect perception as well as reality. With deepfakes and synthetic friends, hallucinations and digital shadows, it’s hard to know what part of our digital collective is real.
Financial advisors, analysts, CIOs, all those corporal inhabitants in our world of finance and asset management, in ten years’ time will they still be human? Investing is all about trust and responsibility. AI doesn’t care.
—Charles Skorina
Read More »OCIO Directory Summer 2026: traditional values
by charles | Comments are closed07/04/2026
Customers may forget what you said but they’ll never forget how you made them feel. – Maya Angelou
Our summer 2026 Outsourced Chief Investment Officer (OCIO) directory features one-hundred-eight service providers with contact names, numbers, and emails for each. Our goal is to help families and institutions locate, review, and connect with full-service discretionary outsource investment managers. No ads, no paywall, no charge.
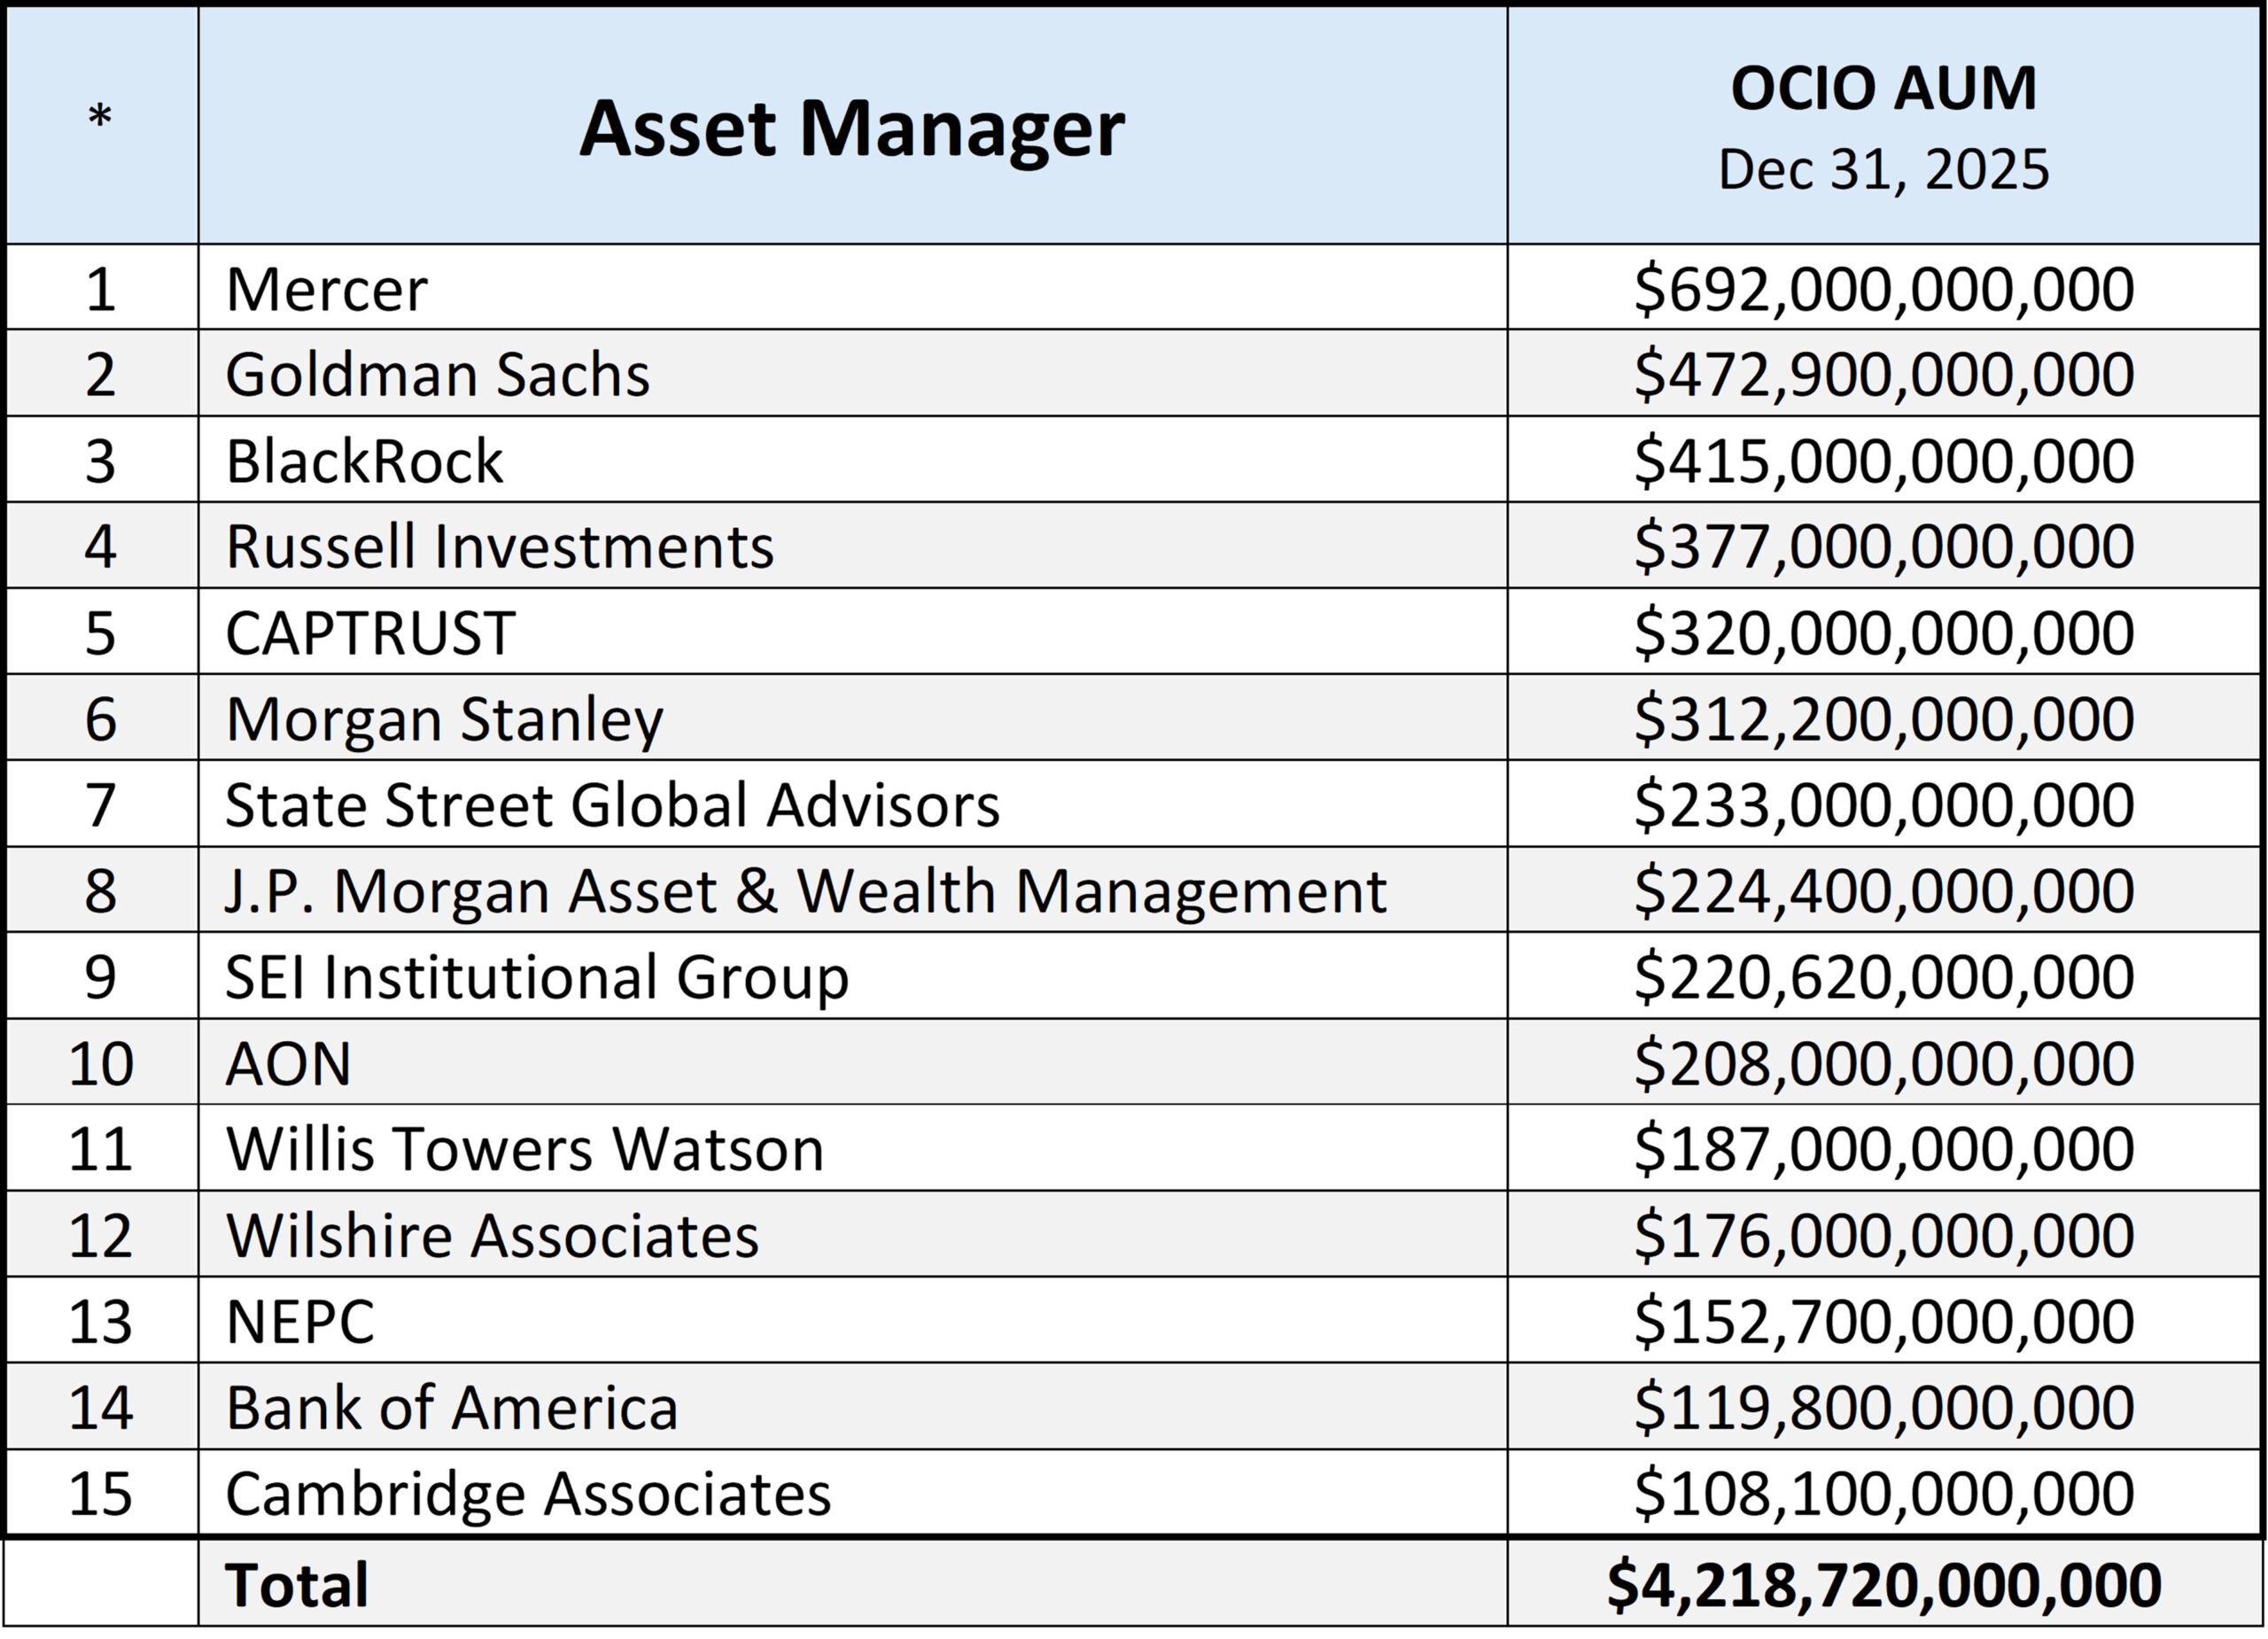
OCIO AUM reached $5.64 trillion at the end of 2025, an 8.9 percent jump ($463bn) from a year ago. And, as usual, the big got bigger. Fifteen firms over one hundred billion manage about seventy-five percent of the assets (mostly pension assets) leaving roughly a trillion four for the pros and pretenders.
Keeping commitments
The outsourced full-discretion investment business is hyper-competitive, hard to differentiate, and expensive to scale, with hundreds of players including RIAs, banks, brokers, and asset managers all competing for institutional and ultra-high-net-worth discretionary mandates. It’s hard to cut through the clutter.
Worse still, few OCIOs are able to convincingly explain their competitive edge or why it should matter. Most firms read the same on paper. So when it comes down to finals, empathy and likeability usually clinch the deal.
My conclusion after years working with both OCIOs and their clients? Families and nonprofits really don’t care about a firm’s “passion for investing.” They care about service and security and keeping promises, not swaps and overlays and some proprietary secret sauce.
Investment performance may rule one out, but it’s seldom the reason for a winning selection.
The OCIO story is a compelling proposition for many institutions and high-net-worth families, but it’s an intensely competitive arena. If you are not taking care of your client, someone else will.
Stepping up, or stepping out
While some OCIOs up their game, others are moving on. FEG and Hirtle & Co. recently rebranded and reaffirmed their commitments, while Cambridge Associates redoubled its efforts and topped $100 billion full-discretion AUM. Organic growth, not M&A.
Others like Mill Creek, Verus, RockCreek, and Russell (yet again?) have decamped for better-resourced patrons. And, just the other day, Fiducient Advisors, part of Wealthspire, now owned by Madison Dearborn Partners, recently announced plans to acquire Sellwood Investment Partners. M&A every which way.
Without a plan for succession and the resources to compete there’s little choice but to sell or merge.
Speaking of which, we have a client, a regional financial corporation with significant multi-state banking and investment operations, who is seeking to augment their full-discretion, investment management capabilities through acquisitions, mergers, and creative partnerships. In short, we’re looking for a few like-minded OCIOs. Call us if you would like to discuss.
Hirtle & Co., fresh paint, time-honored values
While we’re on the subject of client-centric care, take a look at Hirtle & Co.’s recent rebrand, a firm I’ve known for years. In the firm’s letter to clients managing director Susan McEvoy captures the essence of money and mission:
“What matters more to us is what that capital [client AUM] is multiplying in the world: medical research, education, the arts, and the communities we call home; missions that outlast all of us.”
In founder Jon Hirtle’s words, “I joined Goldman right out of the service (The Marine Corps), with a strong sense of idealism and mission. On my first day in training, I asked my mentor to describe ‘the noble cause.’ He immediately replied, ‘The client.’” That said it all.
Who’s who
If a firm says they provide OCIO services, and their website suggests they do, we’ll usually list them upon request.
However, each OCIO has its own culture, client mix, investment style, and biases. Some firms focus on indexing and liquid markets, others on alternatives, still others on ESG. Some customize portfolios for clients, others don’t. Big, small, specialists, generalists, there’s no lack of choice.
Our advice? When shopping for an OCIO, it pays to be thorough. I recently reviewed investment office performance, operations, and talent with the board of a major university. After numerous interviews with trustees and chief investment officers at peer institutions, my final report included one particular caveat: an OCIO relationship is a marriage not a fling. Once a family or foundation commits to a partner, the bond is not easily undone.
—Charles Skorina
(down PDF newsletter & directory)
Read More »Washington University: movin’ on up
by charles | Comments are closed06/07/2026
Diversification is protection against ignorance; it makes little sense if you know what you are doing. —Warren Buffett (1996 annual meeting)
How boards and investment offices make all the difference
Janet Lorin, Bloomberg News, reported recently that Washington University in St. Louis (WashU) could see an astonishing 3000 percent return on their endowment’s $50 million dollar investment in SpaceX.
When asked how this came about, Scott Wilson, WashU’s prescient chief investment officer said, “We try to find really great partners and do interesting things. When they find something that is super attractive we try to add capital to those individual ideas.”
[For a more substantive reveal, here’s a recent interview with Mr. Wilson, courtesy of Ted Seides, Capital Allocators]
There has been a perceptible shift the last few years away from broadly diversified asset-class constructs toward more concentrated portfolios.
Jagdeep Singh Bachher, Ph.D. and chief investment officer at the University of California regents, wrote in UC’s 2025 annual report that his staff intends to invest in fewer, higher quality, top-performing assets.
“Experience has shown us the value of lean, high-performance teams working collaboratively to manage a concentrated, high-conviction portfolio.
We’ve greatly reduced the number of external managers we use and the number of line items on our books. That makes it easier to understand what we own, especially in a crisis, and gives us fewer decisions to make.
The result is a small, agile team laser-focused on areas where we can outperform the market.”
Boards matter
Concentration and high conviction are all well and good, but how many university trustees have the fortitude to weather unruly markets? As it is, the double-edged attacks on university budgets from research cuts and endowments taxes have put schools in serious binds.
Richard J. Chang, reporting for FundFire (an FT service), noted recently that large endowments contribute on average about ten percent to university budgets, (source: Christian Tiu, associate professor of finance at the University at Buffalo School of Management).
However, some schools lean on their endowment for much greater support, in Princeton’s case for example, sixty-five percent of the 2026-27 operating budget.
Mr. Wilson’s winning ways
Embracing risk is a hard sell on campus these days.
As a former Wall Street trader, fly-over college CIO, and staunch individualist, how many schools would have hired Mr. Wilson as chief investment officer do you suppose? When, by our latest count, nearly two-thirds of university CIOs come from peer group endowments.
Fortunately, the WashU trustees spotted a winner and signed him up. And thanks to Mr. Wilson and his investment team, the endowment has moved from fourth to top quartile and even top decile since Scott joined in late Q4 2017.
In our latest endowment performance report, WashU ranked seventh out of one-hundred twenty-two schools over one billion AUM for the ten-year period ending June 30, 2025, doubling in size on Mr. Wilson’s watch from roughly seven billion to over fifteen billion dollars while maintaining a yearly distribution of four to five percent.
The rest of the story . . . (Paul Harvey 1918 – 2009, ABC News Radio)
How WashU built a winning team.
The Washington University in St. Louis endowment had been underperforming its peer group for years and by 2016 the trustees had had enough.
So, the President and board forged a commitment to pursue whatever measures necessary to build a preeminent investment organization – keenly aware that better returns add millions, even billions, to school coffers over time.
In 2016, while he was still CIO of Makena (OCIO), the WashU board asked Eric Upin, an alumnus, university trustee, board chair of the investment management company (and former Stanford CIO) to serve as Interim CIO and Chair of the Search Committee – with emphasis on restructuring portfolio strategy, the investment team, board governance, compensation, and retention.
As a Trustee with full-on university support, Mr. Upin wielded a forceful writ.
The IMC board began their transformation with unvarnished self-reflection and concluded that tentative, short-term thinking was part of their problem. This, in turn, had led to conflicted guidance and mixed signaling to the investment staff.
The board asked:
- What is our primary goal?
- How should we measure success?
- Define the roles of the board and team?
During the year and a half period before hiring Scott Wilson, the board studied the qualities and characteristics of top-performing endowments and portfolios, as well as those that consistently underperformed or fell out of the elite class.
In total, the board spent five years working on governance, compensation, and liquidity management.
Lessons learned
Read More »That one in a million
by charles | Comments are closed02/26/2026

There can be few fields of human endeavor in which history counts for so little as in the world of finance. —John Kenneth Galbraith
I recently reviewed endowment performance and investment talent with the board of a major university. Subjects under discussion included effective board structure, endowment office best-practices, and adaptive leadership for changing times. My assignment is to research and report on investment office successes and failures, all-weather overachievers, and pathways to preeminence.
I’m not alone. A growing number of boards and investment heads suspect the good times and bull market mania might not last and are taking precautions, de-risking and re-thinking conventional portfolio management. Heather Gillers caught the vibe in her recent Wall Street Journal article, “The Ivies Are Having Second Thoughts About Investing in Private Equity.”
We’ve heard rumblings for ages. Howard Marks sounded the alarm three years ago in his memo Sea Change, when he cautioned that the rapid rates reversal and the end of free money would have profound implications for institutional investors:
It seems to me that a significant portion of all the money investors made over [the last forty years] resulted from the tailwind generated by the massive drop in interest rates.
All-weather winners
Managing money is one of America’s key competitive advantages and we recruit the managers who manage the money. What hurts institutional investors and family offices hurts us. If there’s stormy weather ahead, we scout for all-weather chiefs.
Who are the likely winners? Our client would like to know. An iconic venture capitalist once told me he put his money on tenacious, dogged optimists, the ones that assiduously work a problem and never give up.
During last week’s board review, as we discussed high-performance offices and indefatigable overachievers, I recalled an article on genius, and several qualities in particular:
Their openness to new ideas and their breadth of interests infuse them with seemingly irrelevant stimulation that can enrich blind variations.
Hey! I know these folks.
Searching through the haystack
We begin every assignment by looking at the data. Hence our yearly performance reports. Who’s on top and who’s not? Returns may be historical, but they are useful clues to the views, process, and discipline of investors and boards and how well they work together.
Chart one*: Endowment payout levels versus performance

*My thanks to an astute west-coast CIO
As the chart implies, if we assume a four to five percent distribution for university operations, add a few points to pace inflation, and another percent or two for contingencies and growth, the investment office needs to generate an average return of at least 8.15%. Who’s done that?
Our first league table at the end of this note ranks chief investment officers by ten-year returns – data from our January newsletter. Sixty-seven of one hundred schools over one-billion AUM made that first cut, earning eight percent or more for the period. About two-thirds. However, when we raised the bar to nine percent, a more realistic hurdle given all the unknowns, just thirty-two schools remain, one-third the total.
How about career experience and years of service we wondered? How does that factor in?
Turning to the second league table at bottom, with start dates and years in the role, we re-sorted by tenure to spot the correlations between experience and performance.
In the group that generated nine percent or more, the count includes eleven CIOs out of thirty, 37 percent with ten years or more tenure, fifteen CIOs out of forty-three, 35 percent with tenure between five and ten years, and six of twenty-seven CIOs, 22 percent with four years or less.
Experience is important, and a helpful indicator. But there’s more than that to a winning record.
That one in a million
What distinguishes top investment officers? Recruiting talent is both science – can we identify skill and persistence in a candidate’s background? And art – intuition and experience. Is this candidate someone that catches our eye? Piques our curiosity? Are their backgrounds different, interesting, exciting? And how about that second-level thinking Howard Marks refers to?
Here is one example, Ms. Jane Dietze, Brown University’s chief investment officer and perennial chart-topper. Nothing run-of-the-mill about her story.
(Nor Ms. Paula Volent, who frequently held the top spot during her two-decade sway at Bowdoin College, or the many talented women looking for a chance to move up.)
Jane Dietze – Like Mother like Daughter
If you want to know what’s driving Ms. Dietze, you don’t have to look far.
Read More »