If it were easy . . .
by charles | Comments are closed08/18/2026
It takes character to sit with all that cash and to do nothing —Charlie Munger
Jason Zweig – columnist, The Intelligent Investor, WSJ – wrestled recently with one of life’s enduring puzzles. Why do investors so often fall for the myth of the “dazzling investor” and lure of easy money?
Smart, savvy financiers took heady fliers on the media’s latest shooting star, twenty-four year old wunderkind Leopold Aschenbrenner, for example, and so far it’s been a white-knuckle ride.
Investment talent can come from the strangest places, we know, we’ve recruited some zingers over the years. But unless these oracles have had a few hard knocks along the way, they too often believe that this time really is different.
Sooner or later, however, a pesky bear market or related catastrophe gets in the way. Or as Viktor Chernomyrdin, a former Russian Prime Minister once put it, “The thing that never happens just happened again.”
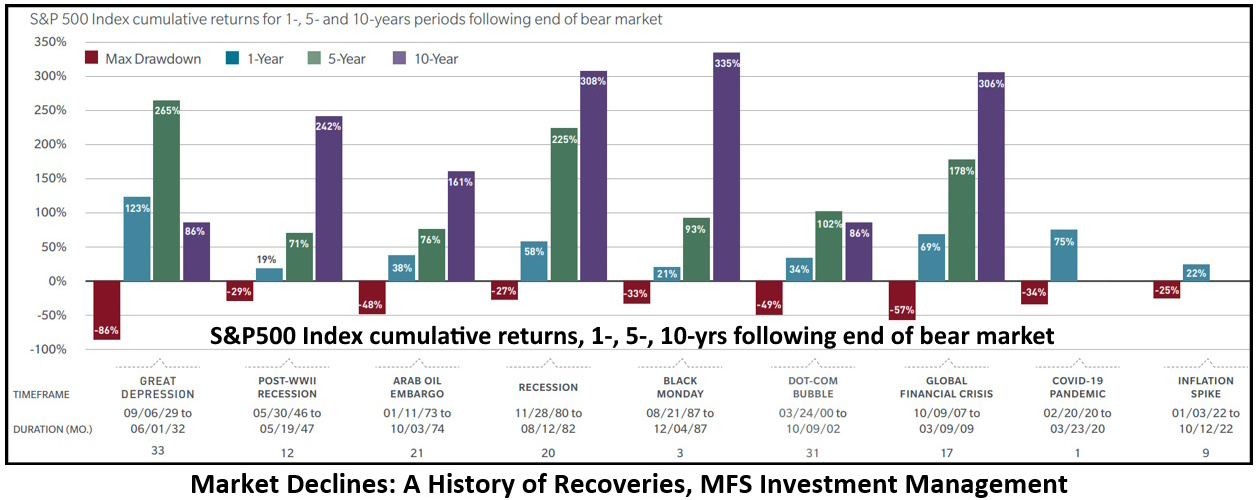
Here’s a chart on past market declines and eventual recoveries.
Link: Market Declines: a History of Recoveries, MFS Investment Management
Even Berkshire Hathaway, with a compounded annual gain of 19.9%, nearly double the S&P 500′s 10.4%, “has had 10 negative return years, four years where it has fallen greater than -20% and six years where it underperformed the S&P500 by more than -20%.”
In Charlie Munger’s final interview he was asked an interesting question. If he and Warren Buffett were in their thirties starting over again today, did he think they could match their past investment success over the next sixty years? He answered this way. They were very intelligent, they worked very hard, and they were very lucky. But could they do it again? Probably not.
How many times in anyone’s life is a person given the opportunity to check all three boxes, he mused. Mr. Buffett, half tongue-in-cheek, once suggested another reason in Berkshire Hathaway’s 2022 Annual Report, “And, yes, it helps to start early and live into your 90s as well.”
As an analyst at Chemical Bank, back during the Mesozoic era, one of my assignments was to follow our Chicago based trading clients. As I soon learned, staying on top of any trader’s book was tough enough. But ascertaining their talent, discipline, and durability was exponentially more challenging. I pored over track records, history, context – statistics not stories, to rephrase psychologist Daniel Kahneman – and still wondered how the best ones did it.
Mr. Zweig’s colleague at the WSJ, Spencer Jakab points out that it can take years, even decades to judge the good from the lucky. (Paradox of Skill, Brad Steiman, DFA). Aschenbrenner’s sole claim to fame was a 165-page essay titled “Situational Awareness: The Decade Ahead,” a paper he wrote in his early twenties.
Markets and economies eventually recover as do great investors like Warren and Charlie — the ones with patience and discipline. We’ll see what Mr. Aschenbrenner learns from his debacle. He’s still in business managing an estimated $10 billion in assets.
In the end, Charlie’s right, it does indeed come down to character, along with brains, grit, and a little luck. As our go-to OCIO maven Jon Hirtle remarks time and again, “serious investors care deeply about keeping their promises.” We couldn’t agree more.
—Charles Skorina
Read More »Better boards, busy bots
by charles | Comments are closed07/29/2026
Making money is art –Andy Warhol
Today’s newsletter is short and mostly sweet. First, helpful hints on building great boards and investment teams, but then some doubts on how much longer it might matter as bot-views and agentic overlords commandeer portfolio management.
Board work matters
A pithy primer on Washington University’s remarkable investment resurgence posted recently on LinkedIn. Clark Hoover, investment officer at the Los Angeles City Employees’ Retirement System read our report on the WashU endowment board’s laudable work and thoughtfully excerpted key dos and don’ts for his nonprofit peers.
When insights come our way – from in-depth interviews with industry veterans, for example – we feel obliged to pass them on to our savvy readers. As ‘frontier’ novelist Louis L’Amour wrote “Knowledge is like money: To be of value it must circulate.”
“What the best boards do:
- Stay aligned and engaged — committed, collaborative, and focused on long-term success.
- Keep governance lean — typically 5–7 members, low turnover, and average board tenure of 10+ years.
- Provide strategic clarity — establish clear objectives, define expectations for the investment team, and evaluate and compensate staff objectively.
- Focus on governance, not management — the board owns strategic asset allocation while empowering investment staff to execute.
What weaker boards tend to do:
- Overcrowd the boardroom — too many voices, high turnover, and excessive micromanagement.
- Send mixed signals — discourage prudent risk-taking while expecting outsized returns.
- Underinvest in talent — reluctance to pay competitively often leads to weaker performance and higher staff turnover.
Strong governance doesn’t guarantee strong investment results—but weak governance makes results much harder to achieve.”
One reader noted, however, that public pensions often have slots set aside for government and union representatives which crowd the boardroom. When it comes to public plans and their financial sway, everyone wants a seat at the table.
Iconoclasts are few and far between and CIOs on many campuses have little room to run, even when they want to. So, if most institutional portfolios look and act the same, why not just give in to AI and the algorithms? It’s cheaper, easier, and when something goes wrong, blame it on those ghosts in the machines.
Sophisticated quant strategies proliferate on Wall Street, ETFs have taken over Main Street, and AI chatbots and robo-advisors swarm financial services. In the world of HR and talent acquisition, algorithms and predictive tools are here in force and impact hiring and career advancement.
Our cyber symbiotes don’t just ease the workload they free us from the tyranny of choice. Decisions without responsibility or regret, every bureaucrat’s dream.
But there are always tradeoffs. Disruptive innovation hits hard and the effects can be brutal. As the automobile swept America, replacing the real life power of horses, entire industries collapsed. Stables, blacksmiths, harness makers, feed suppliers, auction houses, investors; so many livelihoods gone.
So, here’s my worry. These AI dislocations affect perception as well as reality. With deepfakes and synthetic friends, hallucinations and digital shadows, it’s hard to know what part of our digital collective is real.
Financial advisors, analysts, CIOs, all those corporal inhabitants in our world of finance and asset management, in ten years’ time will they still be human? Investing is all about trust and responsibility. AI doesn’t care.
—Charles Skorina
Read More »Cambridge Elevates Recently Appointed President to CEO
by charles | Comments are closed05/14/2016
Institutional Investor article on CAS pay for performance
by charles | Comments are closed03/21/2012
Mellon’s John Hull Tops Non-Profit CIO Pay Rankings
Institutional Investor – March 15, 2012 • Frances Denmark
Charles Skorina had a problem. As an executive search consultant specializing in filling investment officer holes at pension funds and endowments, he was often asked by boards of trustees to produce metrics to aid in candidate comparisons. But in his 30 years in the search business, such data had proved hard to come by — that is, until late January. That’s when Skorina’s “CIO Performance-for-Pay” ranking (see chart below) hit the institutional investor zeitgeist.
Read More »Bloomberg: Help Wanted on Campus – Top U.S. universities are looking for a new breed of investment manager who can be nimble in tough times.
by charles | Comments are closed08/18/2010
Bloomberg: Help Wanted on Campus
By Gillian Wee – Aug 18, 2010
Bloomberg Markets Magazine
Top U.S. universities are looking for a new breed of investment manager who can be nimble in tough times.
Read More »